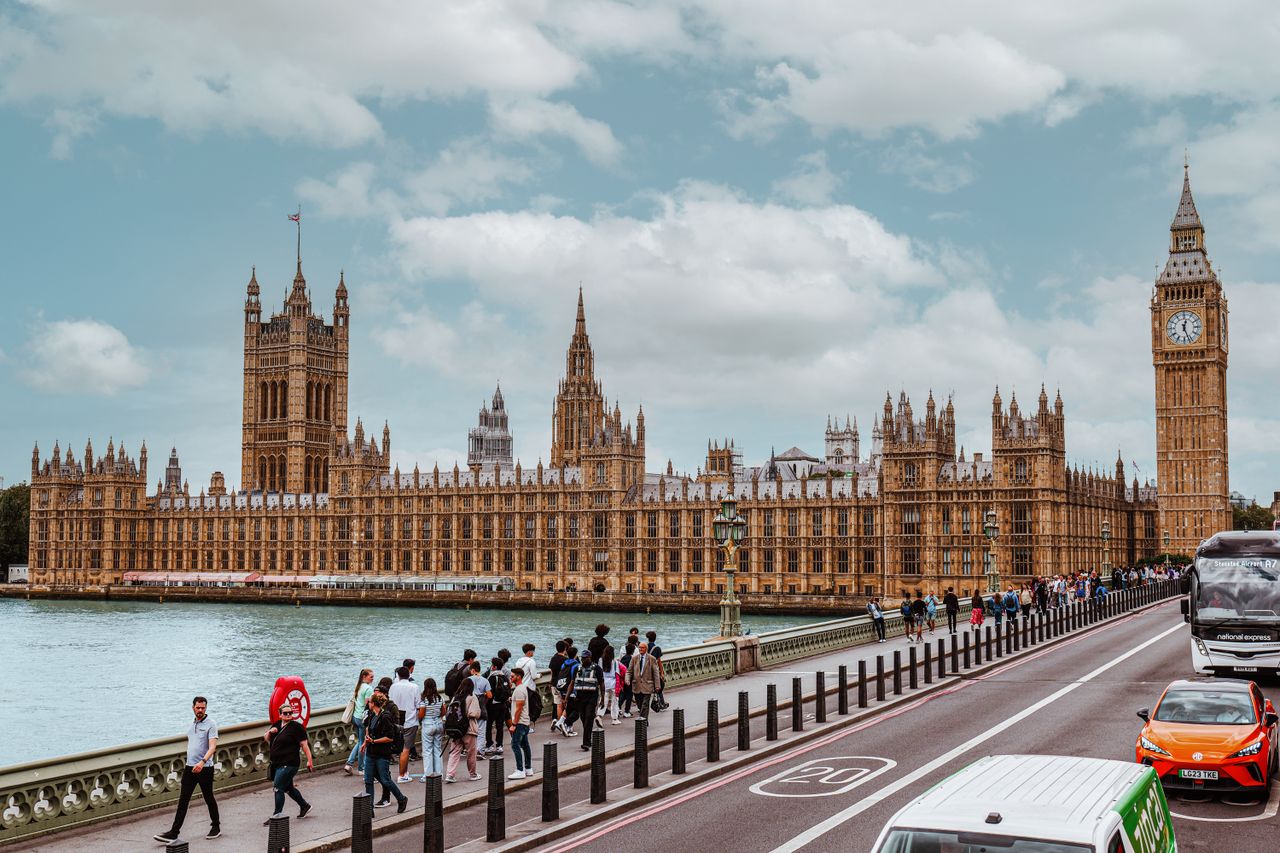
A new era for tourism taxation could be approaching in England.
The government has announced plans to give mayors and other strategic local authorities the power to introduce an Overnight Visitor Levy on paid accommodation, including hotel and Airbnb-style stays. The proposal is part of a broader effort to move financial and policy powers away from Westminster and toward local leaders.
For travelers, the concept is simple: an additional charge would be added to the cost of staying overnight in participating areas.
For local governments, however, the implications are much larger.
The levy could generate new money for public transport, high streets, public spaces, events, cultural attractions and other projects designed to improve both residents’ quality of life and the visitor experience.
For the hotel and hospitality industry, the picture is considerably more controversial.
Industry groups have warned that an uncapped levy could increase the cost of already-expensive UK holidays, create additional administrative work for accommodation providers and potentially reduce tourism-related economic activity. UKHospitality has cited modelling suggesting that a 5% levy could eventually be associated with a £2.2 billion reduction in economic output and around 33,000 fewer jobs.
Supporters point to a very different conclusion.
They argue that small visitor levies are common internationally, can help destinations pay for infrastructure used heavily by tourists and do not necessarily cause significant falls in visitor numbers. Experience from places such as Manchester and Edinburgh is already becoming part of the debate.
The argument is therefore no longer whether tourism should contribute more directly to the places it uses.
The question is how the system should work—and who should pay, who should benefit and how much.
What Is England’s Overnight Visitor Levy?
The proposed Overnight Visitor Levy is essentially a form of tourist tax charged when people pay for overnight accommodation.
Under the government’s current plan, it would apply to paid overnight stays rather than to people simply entering or visiting a destination for the day. The levy would be calculated as a percentage of the accommodation price, rather than a fixed amount per night.
That design is significant.
A fixed £2 or £3 charge affects a budget hotel and an expensive hotel in exactly the same way.
A percentage-based system means the charge rises with the price of the accommodation.
The government says this approach is intended to protect cheaper holidays from a disproportionate additional cost.
But it also means that a traveler staying in an expensive hotel could pay substantially more than someone staying in budget accommodation.
There Is No National Rate Yet
One of the most important facts for travelers is that England does not yet have a single national tourist-tax rate.
The government has proposed giving local leaders the power to introduce the levy, but the rate would be set locally. The government has said there would be no national cap, although it expects any rate to be proportionate.
That creates the possibility of different tourism-tax systems across England.
London could have one rate.
Greater Manchester could have another.
A coastal tourism region could choose a different approach.
Another area might decide not to introduce a levy at all.
This means England could eventually have a patchwork of visitor charges rather than one uniform national tourist tax.
Why the Government Wants Local Leaders to Have the Power
The levy is closely tied to the government’s wider devolution agenda.
Ministers argue that local leaders are better placed than central government to decide how tourism-related revenue should be raised and spent in their regions.
The government says the money could support investment in high streets, public transport, public spaces and events, helping communities capture more of the economic benefits generated by tourism.
This is important because tourism can impose costs locally.
Visitors use roads.
They generate waste.
They increase demand for public transportation.
They visit parks and cultural attractions.
They place pressure on public spaces.
They require policing, cleaning and maintenance.
In some destinations, the same infrastructure must accommodate a population that is temporarily much larger than the permanent resident population.
Supporters argue that it is reasonable for visitors to contribute something toward those costs.
This Is Also a Test of Fiscal Devolution
The proposal has significance beyond tourism.
Giving local leaders authority over a locally raised source of revenue represents a meaningful shift in how public finances operate.
Instead of relying entirely on money transferred from central government, regions would have another mechanism for raising funds associated with their own economic activity.
The government’s broader devolution plans include additional changes to how local authorities retain and manage revenues. The visitor levy is therefore part of a much larger experiment in regional fiscal power.
That makes the tourism-tax debate partly a constitutional and economic debate.
How much money should local areas be allowed to raise?
How much flexibility should mayors have?
What safeguards should exist?
How much control should central government retain?
Tourism happens to be the issue through which those questions are being tested.
Who Would Pay the Levy?
The charge would generally apply to people paying for overnight accommodation.
That could include travelers staying in hotels, short-term rental properties and other paid accommodation, although individual schemes may determine exemptions and the precise scope. The government has indicated that mayors could allow exemptions for some categories, including certain campsites, while shelters and refuges would be automatically exempt.
The policy would therefore be broader than a tax that applies only to traditional hotels.
That matters because the accommodation market has changed significantly.
Visitors can now choose from hotels, serviced apartments, guesthouses, hostels, holiday rentals, holiday parks and other forms of short-term lodging.
If only hotels were taxed, some businesses could gain an artificial competitive advantage.
Including Airbnb-style accommodation is therefore an important part of the policy debate.
Why Airbnb and Short-Term Rentals Are Central to the Debate
Short-term rental platforms have changed tourism in cities and coastal communities.
They have expanded accommodation capacity.
They have created new income opportunities for property owners.
But they have also generated concerns about housing supply and neighborhood pressure in some destinations.
A visitor levy applied to hotels but not comparable short-term rentals could distort competition.
That is one reason policymakers are considering a broader accommodation-based approach.
At the same time, taxing short-term accommodation creates practical enforcement questions.
How does a local authority track thousands of individual properties?
Who is responsible for collecting the charge?
How are bookings made through international platforms handled?
How can authorities prevent under-reporting?
These administrative questions could become just as important as the headline rate.
The Government Wants to Protect Budget Holidays
One of the most interesting policy choices is the decision to use a percentage rather than a flat fee.
The government argues that this automatically makes the system more proportional.
Suppose two people stay at a low-cost hotel.
A fixed £3 nightly charge would represent a relatively large percentage of their accommodation cost.
A percentage levy would generate a smaller amount.
By contrast, visitors staying at a luxury hotel would make a larger contribution.
This structure resembles the model adopted in Edinburgh, where the visitor levy is 5% of the cost of paid accommodation and applies for up to the first five consecutive nights.
However, the English proposal differs in an important way because no national maximum rate has been specified.
The Biggest Controversy: There Is No National Cap
Hospitality groups have focused heavily on the fact that the English proposal would not impose a national cap.
Officials say the levy should be proportionate, but the absence of a statutory ceiling leaves the ultimate rate in local hands.
That has created concern among hotel operators.
A 1% levy is one thing.
A 5% levy is another.
A substantially higher charge would be different again.
Businesses therefore want to know what safeguards will exist before making pricing and investment decisions.
The government’s position is that local leaders need flexibility.
The industry’s position is that businesses need certainty.
That tension is at the heart of the debate.
Several Mayors Are Already Signaling Their Preferences
Although the national framework is still being developed, some local leaders have already discussed limits.
London Mayor Sadiq Khan’s office has indicated that any London levy would not exceed 5%, while other Labour metro mayors have also indicated support for keeping rates around that level.
At the same time, some Conservative and Reform UK mayors in eastern coastal areas have said they do not intend to introduce the tax.
That illustrates another important feature of the system.
There may be competition between regions not only over whether to introduce a levy, but also over its level.
Some destinations could market themselves as having no visitor levy.
Others could argue that a levy provides better-funded streets, events and visitor services.
England Would Not Be Inventing the Idea
Tourist taxes are common internationally.
Cities and regions across Europe have used overnight accommodation charges for years.
They exist in destinations such as Rome, Amsterdam, Barcelona and Venice, among many others. Similar schemes also exist in North America and elsewhere.
That makes England something of a late adopter.
The argument for the levy is therefore not that England is pioneering an entirely new tax.
It is that England is catching up with a well-established international tourism model while adapting it to a highly decentralized regional system.
Edinburgh Has Already Taken the Step
Scotland offers perhaps the most relevant nearby example.
Edinburgh’s visitor levy came into effect on July 24, 2026.
The city charges 5% of the cost of paid overnight accommodation, applies it to the first five consecutive nights and covers accommodation types including hotels, hostels, guesthouses, self-catering properties and short-term lets.
The city expects the levy to raise as much as £50 million annually once established.
Importantly, Edinburgh has already begun deciding how the funds will be used.
Investment plans include street cleaning, green spaces, safety, infrastructure, cultural and heritage projects, visitor management and support for cultural organizations. The council has also committed £2 million of levy income toward participatory budgeting over three years.
That gives England a real-world example to observe.
Manchester Has an Even Longer Track Record
Manchester became the first UK city to introduce a local visitor charge in 2023.
The city’s £1 per-night model has generated more than £10 million over its first three years for cultural and visitor-related investment, according to current reporting. Research cited by the Guardian has found no significant effect on hotel occupancy.
Manchester’s experience is particularly relevant because it demonstrates that a visitor levy does not necessarily need to be large to generate meaningful revenue.
A small contribution multiplied across millions of overnight stays can become substantial.
The challenge for policymakers is ensuring that the economic value created by the spending outweighs any deterrent effect from the additional cost.
Liverpool Has Also Introduced a Charge
Liverpool has followed the Manchester approach with a £2 visitor charge.
The scheme has generated more than £2 million, according to recent reporting.
Together, Manchester and Liverpool provide useful evidence for the argument that Britain can operate small accommodation levies without automatically damaging tourism.
But England’s new proposal is potentially different because the local powers are broader and the levy is designed as a percentage rather than a nationally standardized small flat fee.
Wales Is Taking Another Approach
Wales also plans to introduce a visitor levy.
The Welsh system is expected to allow councils to charge a flat fee of £1.30 per person per night for most accommodation from April 2027.
That creates an interesting comparison.
England is leaning toward a percentage.
Scotland is already using a percentage model in Edinburgh.
Wales is moving toward a flat charge.
The three systems will provide an unusually useful natural experiment for policymakers.
Which System Is Fairer?
There are strong arguments on both sides.
A percentage system means people staying in expensive accommodation contribute more.
That can be seen as progressive.
But a percentage system also makes the absolute charge more significant in premium hotels, potentially affecting business travelers and luxury tourism.
A flat fee is simple and predictable.
But it can represent a much larger proportion of the cost for someone staying in the cheapest available accommodation.
There is no perfect model.
The appropriate design depends partly on what policymakers are trying to accomplish.
What the Hospitality Industry Is Worried About
Hospitality businesses are already dealing with significant cost pressures.
Labor costs have increased.
Energy remains a major concern.
Insurance can be expensive.
Food and supply prices fluctuate.
Consumer spending is under pressure.
The hotel industry therefore argues that another accommodation-related charge could further reduce competitiveness.
UKHospitality has cited analysis projecting that a 5% national-level levy by 2030 could cost around £2.2 billion in economic output and be associated with approximately 33,000 job losses.
The organization has also argued that British hospitality businesses already operate under a comparatively high VAT burden.
From the industry’s perspective, another charge risks making UK accommodation more expensive relative to European alternatives.
The Industry’s “Staycation” Argument
One of the most politically powerful objections is that the tax could hurt British families taking domestic holidays.
A family booking a hotel for several nights during school holidays already faces high accommodation prices.
Adding a percentage levy increases the total.
At some point, critics argue, families may decide it is better value to travel overseas.
That would be particularly problematic for domestic tourism destinations such as coastal towns and rural regions that depend heavily on British holidaymakers.
The industry has therefore warned that what appears to be a modest tax on paper could have a larger psychological effect when consumers compare final holiday prices.
But Evidence From Other Destinations Tells a Different Story
Supporters point to international evidence showing that tourist taxes do not necessarily drive visitors away.
Amsterdam, Barcelona, Venice and many other destinations impose accommodation levies without eliminating tourism demand.
Research discussed by the Guardian has found no clear evidence that such taxes systematically deter tourists, while local revenues can support tourism infrastructure and public projects.
This does not prove that any levy at any rate will have no economic impact.
It does suggest that a modest, well-designed tax is not automatically a tourism killer.
The rate and the destination matter.
So does what visitors receive in return.
The “Value for Money” Question
Tourists are generally more tolerant of additional charges when they can see the benefit.
If a visitor pays £10 or £20 in taxes but encounters clean public spaces, reliable transport, well-maintained attractions and vibrant cultural events, the charge can feel more reasonable.
If the visitor pays more and sees no improvement, the tax becomes much harder to justify.
This is why transparency could be one of the most important factors in the success of England’s system.
Visitors will want to know:
Where did the money go?
What did it pay for?
What changed?
Did the town become cleaner?
Did public transport improve?
Were historic attractions preserved?
Were events expanded?
The answer to those questions may determine public acceptance more than the tax rate itself.
Tourism Taxes Can Fund Things Visitors Rarely Notice
Not every benefit has to be an attraction.
A visitor may never consciously notice extra street cleaning.
They may not know that a public toilet was renovated with levy revenue.
They may not recognize that signage was upgraded or a bus service improved.
But those investments can affect the overall quality of a destination.
Tourism is an ecosystem.
A clean, safe, accessible and attractive city is part of the tourism product even when no one buys a ticket for it.
This Could Be Particularly Important for Coastal Towns
Coastal destinations can experience enormous seasonal swings.
A town may have a relatively small permanent population but receive a dramatically larger number of visitors during the summer.
That creates unusual pressure on public infrastructure.
A visitor levy could allow local authorities to capture some revenue specifically during the periods when tourism demand is highest.
It could then be spent on services that benefit both tourists and residents.
The challenge is ensuring that the money genuinely stays connected to the destination rather than disappearing into a broad local budget.
Rural Tourism Faces a Different Challenge
A rural destination may have fewer hotel rooms and visitors spread across a much larger geographic area.
Visitors may stay in guesthouses, holiday cottages, campsites and private rentals rather than conventional hotels.
That makes collection more complicated.
At the same time, rural areas may depend heavily on tourism for employment.
A levy that is too high could potentially hurt demand in places where alternatives are easier to find.
Local authorities will therefore need to design systems appropriate to their tourism economies rather than assuming that an approach that works in a major city will automatically work in the countryside.
London Is a Special Case
London attracts visitors from around the world and has an enormous accommodation market.
Even a small percentage charge could generate significant revenue because of the volume and price of hotel stays.
The city’s mayor has indicated that any levy would be capped at 5%, according to current reporting.
The bigger question will be how London decides to use the money.
Transport is an obvious candidate.
So are public realm improvements, cultural institutions and visitor infrastructure.
But London also has a highly competitive hotel market, meaning pricing responses could be more complicated than in smaller destinations.
Business Travelers Will Be Affected Too
A “tourist tax” is an appealing name politically, but the levy would not necessarily be paid only by vacationers.
The proposal concerns paid overnight stays.
That means a person traveling to England for a conference, business meeting or work assignment could potentially pay the levy as well.
That is consistent with many international visitor-tax systems.
Edinburgh, for example, applies its visitor levy to paid accommodation regardless of whether the reason for the stay is tourism, work or another form of visit.
This broadens the economic implications.
Business travelers can be particularly valuable to hotels because they may travel during weekdays and outside peak holiday seasons.
Will the Levy Make England More Expensive Than Europe?
That depends on the rate.
Many European destinations already impose overnight taxes, often in the range of a few euros per person per night or as a percentage of accommodation costs.
England therefore would not necessarily become unusual simply by introducing a levy.
But the industry’s concern is that an uncapped system could eventually produce rates above those of competing destinations.
That is why business groups have emphasized the need for a cap.
They fear that local competition could evolve into a race in the opposite direction.
Could Local Authorities Compete Through Lower Taxes?
There is another possibility.
Instead of every region charging the maximum possible amount, destinations could use their levy rate as part of a broader competitiveness strategy.
A coastal city might choose a low levy because it competes with neighboring resorts.
A major cultural destination might choose a higher levy because it offers a more extensive visitor experience.
A region with severe infrastructure pressure might decide that the revenue is worth the additional cost.
In other words, tax competition could become part of regional tourism policy.
The Administrative Challenge Could Be Significant
Collecting a visitor levy sounds easy.
In practice, it requires systems.
Accommodation businesses need to identify taxable transactions.
Rates have to be calculated correctly.
Exemptions need to be handled.
Records must be maintained.
Money has to be transferred to the relevant authority.
Authorities need mechanisms for audits and enforcement.
Short-term rentals add another layer.
Small guesthouses may have limited administrative capacity.
Large hotel chains may have sophisticated accounting systems.
A good national framework will need to minimize the compliance burden while still preventing large-scale leakage.
Booking Platforms Could Become Central Players
Companies operating accommodation marketplaces may eventually become part of the collection system.
That could make tax collection more efficient because a platform can potentially add the levy automatically at checkout.
But it could also create questions about data sharing, liability and how overseas companies interact with local authorities.
The final legislation will matter greatly here.
Exemptions Will Shape the Real Impact
The government has said mayors could introduce exemptions for certain accommodation types and that shelters and refuges would automatically be exempt.
Local authorities may face pressure to exempt:
Campsites.
Youth accommodation.
Emergency housing.
Certain workers.
Long-term residents.
People displaced by local emergencies.
The more exemptions there are, the more complicated the system becomes.
But too few exemptions could create genuine fairness problems.
What Happens to Residents Staying Locally?
Another important question is whether the tax applies only to foreign tourists.
The answer in comparable visitor-levy systems is generally no.
Edinburgh’s system applies to UK and Scottish residents who pay for overnight accommodation in the city, not merely to international visitors.
That means an English family taking a weekend break in another English region could potentially pay the same levy as an international tourist.
The term “tourist tax” can therefore be somewhat misleading.
“Visitor levy” is a more accurate description.
Could the Levy Encourage Day Trips Instead?
One concern is that higher overnight costs could push some travelers toward day trips.
A visitor who might have stayed two nights could choose to arrive early and leave late.
That would reduce accommodation spending while still generating pressure on roads, attractions and public spaces.
However, the opposite could also happen.
If levy revenue improves infrastructure and visitor experiences, it could encourage longer stays.
Again, design and spending matter.
The Most Important Metric May Be Length of Stay
Tourism economists often look beyond visitor numbers.
A destination receiving 100,000 visitors who stay one night can generate less economic activity than one receiving 80,000 visitors who stay four nights.
This is why local tourism strategies increasingly focus on increasing the value of visits rather than simply maximizing arrivals.
A modest accommodation levy may have little economic effect if visitors continue extending their stays.
A high levy that causes tourists to shorten trips could have more serious consequences.
Local authorities will need data to understand that relationship.
Cultural Attractions Could Be Major Beneficiaries
Tourist-tax revenue has considerable potential for museums, festivals, galleries, theatres and heritage sites.
These institutions often provide the experiences that attract visitors but do not always generate enough commercial revenue to maintain themselves.
Edinburgh has already earmarked levy funding for cultural organizations and heritage locations, as well as for maintaining the city’s cultural offer throughout the year.
England’s regions could adopt similar strategies.
That could be particularly valuable in historic towns where heritage is central to the tourism economy.
Events Can Be Another Smart Investment
Tourism is often highly seasonal.
Events can help fill hotel rooms during quieter periods.
A local authority could use levy revenue to support festivals, concerts, food events, sporting competitions or cultural celebrations.
That creates a circular effect.
The levy funds the event.
The event attracts visitors.
Visitors spend on hotels and restaurants.
Those businesses employ local people.
The regional economy gains.
A Well-Designed Levy Could Become a Tourism Investment
That is probably the strongest argument for the policy.
Instead of treating tourism as a source of costs, local governments can treat it as a source of investment.
The levy becomes a mechanism for taking a small share of visitor spending and putting it back into the destination.
When done transparently, this can create a feedback loop:
Better infrastructure creates better experiences.
Better experiences attract more visitors.
More visitors generate more revenue.
More revenue supports further improvements.
But Poorly Designed Tourism Taxes Can Backfire
The opposite is also possible.
A destination could impose a high levy.
Spend the revenue on unrelated priorities.
Fail to improve visitor infrastructure.
Make booking more complicated.
And still expect tourists to remain enthusiastic.
That would undermine the entire case for the policy.
This is why transparency and accountability are so important.
The Spending Rules May Matter More Than the Tax Rate
When travelers complain about a tourist tax, they are often reacting not only to the amount but also to the principle.
They may think:
Why am I paying this?
What does it fund?
Why does the destination need more money?
If authorities can provide clear answers, resistance may be lower.
Edinburgh offers one possible model, with clearly defined investment themes around city operations and infrastructure, culture and heritage, and destination and visitor management.
England’s local authorities could learn from that approach.
Tourism Taxes and Housing Pressure
Some local leaders may also be tempted to connect tourism-tax revenue with housing policy.
That would be politically sensitive.
Short-term rentals can compete with long-term housing in some markets, while tourism workers themselves may struggle to find affordable accommodation.
Edinburgh has already used the visitor-levy framework to support housing-related initiatives, reflecting the connection between the visitor economy and local housing pressures.
England’s local authorities may face similar debates.
Should tourism revenue support housing for tourism workers?
Should it improve public transport so workers can live farther from expensive city centers?
Should it help manage short-term rentals?
Those choices could shape the social impact of the levy.
The Policy Could Change the Economics of Holiday Lets
Short-term rental hosts will need to understand their responsibilities under any local scheme.
A property charging £150 per night would have a different tax impact from a £60 property under a percentage-based system.
That could affect pricing decisions.
Hosts might absorb some of the cost.
They might pass all of it to guests.
Or they might raise base prices slightly to preserve their margins.
The same dynamics apply to hotels.
So the real consumer impact cannot be predicted simply by looking at the headline levy rate.
Travelers May Not Notice the Tax at First
If a booking website displays the accommodation price and the levy separately, the additional cost will be obvious.
Some platforms may incorporate it into the total price.
Others may show it separately at checkout.
The government’s eventual regulations will determine how transparent the charge must be.
That matters because so-called “hidden fees” can generate more consumer frustration than clearly disclosed taxes.
Comparison Shopping Could Become More Complicated
Travelers already compare hotel prices across cities and countries.
A regional tourist tax adds another variable.
A £120 hotel room in one city and a £120 room in another may no longer have the same final cost if their local levy rates differ.
Travel companies and booking platforms will therefore need to make tax-inclusive pricing easy to understand.
Hotels May Respond in Different Ways
Large hotel chains could absorb a portion of the charge as a competitive strategy.
Independent hotels may have less room to do so.
Luxury properties may pass the full amount through more easily because the levy represents a smaller percentage of total trip spending for affluent customers.
Budget hotels may face greater pressure because their customers are more price-sensitive.
The effect could therefore differ significantly by market segment.
A Higher Levy Could Shift Demand Between Regions
Suppose one city charges 5% and a neighboring destination charges nothing.
Some visitors may switch.
Others will consider the attractions, transport links and accommodation quality more important.
This is why local leaders cannot assume that a levy will produce revenue without affecting behavior.
They will need to understand their own competitive position.
The UK Could Eventually Have Three Different Models
With England moving toward a percentage-based local levy, Scotland already operating Edinburgh’s 5% system and Wales preparing a flat-rate approach, the United Kingdom could soon become a laboratory for different forms of tourist taxation.
That could be useful.
Researchers will eventually be able to compare:
Visitor numbers.
Hotel occupancy.
Average room rates.
Length of stay.
Tax revenue.
Employment.
Tourism spending.
Business investment.
Those comparisons could reveal which model works best under different conditions.
What the Current Timeline Means for Travelers
The new English system is not an immediate nationwide tax appearing on every hotel bill.
The government still needs to develop and pass legislation and establish the framework through which strategic authorities can use the power.
Government plans indicate that local leaders should have the power to introduce the levy as part of the wider devolution process, with local investment plans set out by March 2028.
That means travelers should not assume that an English tourist tax will suddenly apply everywhere at the same time.
The system is likely to emerge region by region.
What Tourists Should Watch For
The most important details will eventually be:
The local rate.
Which types of accommodation are covered.
Whether there is a maximum number of nights.
What exemptions apply.
How the charge appears on booking websites.
Where the money will be spent.
How businesses will collect it.
Whether neighboring regions adopt different rates.
Those factors will determine how noticeable the levy becomes.
Why the Debate Matters Beyond England
Tourism taxes are becoming more common as destinations confront a difficult reality.
Visitors generate money.
But they also generate costs.
The challenge is to find a fair way to balance the two.
If tourism revenue is left entirely with private businesses while public authorities absorb the cost of cleaning streets, maintaining infrastructure and managing visitor pressure, residents may reasonably ask why tourists do not contribute directly.
On the other hand, if governments use tourism taxes simply as a convenient way to raise general revenue, businesses and visitors may reasonably question the value.
The legitimacy of the tax depends on the connection between payment and benefit.
Final Takeaway
England’s proposed Overnight Visitor Levy could fundamentally change how the country finances tourism.
Instead of treating visitor spending as something that happens to local economies, the policy would give regional leaders a direct mechanism to capture a portion of accommodation spending and reinvest it.
The proposed system is deliberately flexible.
It would be charged as a percentage of accommodation costs rather than a flat amount, would apply to paid overnight stays and could be introduced locally rather than imposed uniformly across England. The government says cheaper accommodation would automatically face a smaller charge, while local leaders would decide whether to introduce a levy and how revenues should be invested.
That flexibility is also the policy’s greatest uncertainty.
Without a national cap, travelers and hospitality businesses do not yet know how high local charges could eventually become.
Industry groups warn that a poorly designed levy could raise holiday costs, reduce demand and threaten jobs.
Supporters point to Manchester, Liverpool and Edinburgh and argue that well-designed visitor levies can raise substantial sums without destroying tourism demand.
The most important lesson may therefore be simple:
A tourist tax is neither automatically good nor automatically bad.
Its success will depend on the rate, the exemptions, the collection system, the transparency of spending and the quality of the destination that visitors receive in return.
For travelers, the era of the completely tax-free English hotel bill may eventually become less common.
For local governments, the bigger opportunity is to turn a small charge on overnight stays into a long-term investment in the places millions of people come to visit.
5 Frequently Asked Questions
1. Is England introducing a nationwide tourist tax?
Not exactly. The government plans to give mayors and other strategic local authorities the power to introduce an Overnight Visitor Levy. It would therefore be optional and could vary from one region to another rather than automatically applying across all of England.
2. How much will England’s tourist tax cost?
No single national rate has been fixed. The government says the levy would be a percentage of accommodation costs rather than a flat nightly fee, and there would be no national cap. Some local leaders have indicated that they would keep rates around 5%, but individual authorities will ultimately determine their own schemes within the legislation.
3. Will Airbnb and short-term rentals be included?
The policy is intended to cover paid overnight accommodation, including hotel and Airbnb-style stays. The final legislation will determine the precise categories and exemptions, while local authorities may have some flexibility over accommodation such as campsites.
4. Where will the money from the levy go?
Local leaders will be able to decide how the revenue is invested. Government proposals highlight areas such as high streets, public transport, public spaces and events, while existing visitor-levy schemes elsewhere in the UK are also funding cultural, heritage, cleanliness, safety and visitor-management projects.
5. Will a tourist tax make holidays in England more expensive?
Yes, for visitors staying in areas that introduce a levy, the final accommodation cost will increase unless the accommodation provider absorbs some or all of the charge. However, the size of the increase will depend on the local rate and the price of the accommodation. Evidence from existing schemes such as Manchester’s and Edinburgh’s suggests that a moderate levy does not necessarily produce a major fall in tourism, although hospitality groups argue that higher rates could have broader economic consequences.
Sources The Guardian